One of the worst kept secrets in the industry is now official … Asset Care enhancements have been announced.
There are a few states where the changes are pending approval so be sure to check with either your BGA/MGA/FMO/IMO or the OneAmerica Sales Desk if you have any questions. Here is the state approval map as of today – APPROVAL GRID.
There are two distinct enhancements to the product. One is benefits related and the other is funding focused.
First the benefits – since Asset Care 2024 was launched, there has been criticism of the death benefit portion of the product being a little lacking. Well, those comments were heard and addressed in this product enhancement.
You will now have an option to choose between a higher death benefit or richer LTC benefits. When you elect for the higher death benefit, there is a trade-off. This trade off is for the acceleration of benefits (AOB) portion only … simply, with a higher death benefit, the AOB will be 36 months (3 years).
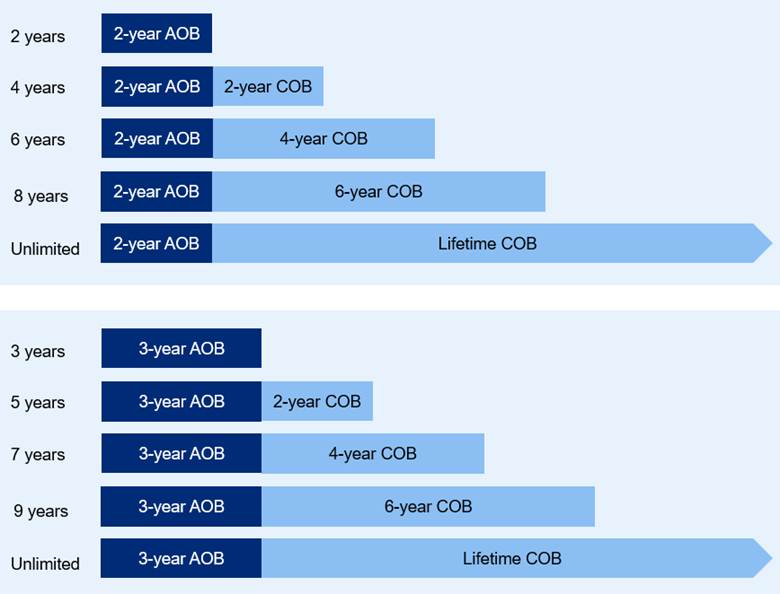
The Continuation of Benefits Rider (COB) remains unchanged as do the inflation options. And, remember, that the OneAmerica Care Benefits Concierge is included with every policy issued.
Just a reminder, Asset Care can be funded the following ways:
- Recurring Premium (5, 10, 20 years or to age 95)
- Recurring premium with a dump-in
- Single premium cash
- Single premium 1035 exchange from life insurance
- Single premium with a recurring premium for the COB
- Single premium qualified money
You will note that qualified money funding is highlighted. This is the other enhancement that has been made to Asset Care.
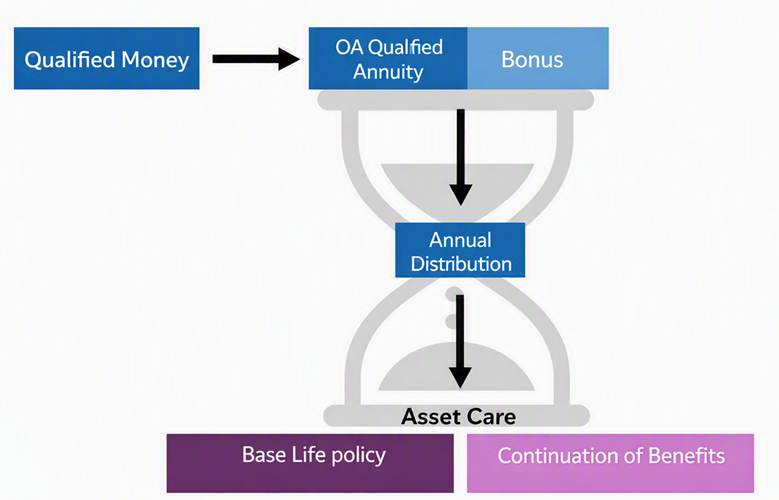
To refresh your memory, the IRA is rolled over (tax-free) to OneAmerica and into a qualified deferred annuity. Upon receipt of the rollover monies, a bonus is applied then that money is distributed (and taxed) over a period of time to fund the Asset Care policy.
Up until this revision, that was limited to a 10 year period. Effective September 21 in the states that have approved the enhancements, there are payout options for 5 years, 10 years, or 20 years. And, correspondingly, the rollover bonuses will be unique to each payout duration.
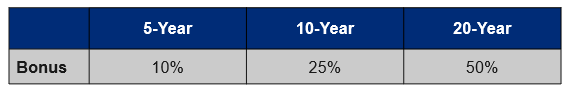
As you would expect, this will have an impact on the payout. Here is an example of how a $200,000 rollover would look for a couple, both age 60, with a lifetime benefit and no inflation.
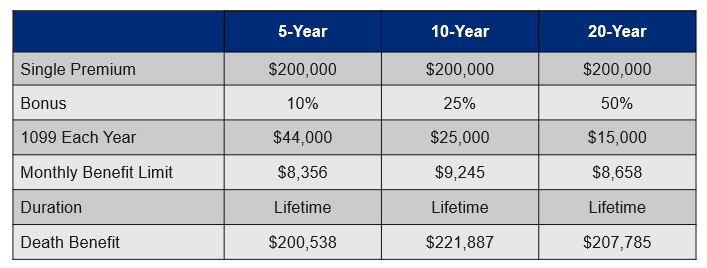
Remember this – the 5 year and 10 year strategies may work well for non-spouse beneficiaries of inherited IRAs. Remember, the SECURE Act requires that inherited IRA to be liquidated before the end of the 10th year. (Note: you can illustrate this to age 35.)
You will also find a new producer brochure that discusses using qualified money as a premium source. Check it out … Qualified Money Brochure.
There you have it – Asset Care enhancements in 2026.
If you have any questions, contact my internal Kelley Hilliard at (844) 623-4251.


Leave a comment