“Why do you think I’m the best player in the world? Because I never get bored with the basics. I never get bored with the basics.” Kobe Bryant
This week, I want to get back to the basics – the fundamentals of asset-based LTC using Care Solutions products.
Asset-based (aka linked-benefit) LTC has been in existence for almost 40 years. OneAmerica Financial is one of the pioneers in this line of insurance introducing it originally as Spouse Care as the Golden Rule Company. (Note: There is only one other carrier has a similar commitment and experience in the arena.)
IMPORTANT – asset-based LTC is a long-term care funding strategy. It is NOT an income doubler on an annuity or a chronic illness rider attached to a life insurance policy. IT IS LONG-TERM CARE!
All asset-based products like Asset Care & Annuity Care follow the same principles. Simply, with asset-based long-term care, the policy holder will receive benefits on way or another.
- If they need to pay for LTC, there is money available;
- if they don’t ever need it, money is passed to whomever they want; and
- if they want to walk away, there can get some, all, or more than what they put into the policy (depending on how they fund it).
It’s the live, die, or quit story.
Another thing to remember … the care solutions products are loaded with guarantees. Guaranteed premiums (they can never increase) and guaranteed benefits (what you see is what you get). Every element carries guarantees!
The next thing to remember is the configuration of the product. You will find a base portion (a deferred annuity or life insurance policy) and a continuation of benefits rider (COB). The COB, for tax purposes, qualifies as LTC insurance under IRC 7702(b). With both Asset Care and Annuity Care, the COB can either be a finite pool or an unlimited stream of resources (the only carrier in the LTC industry to offer unlimited benefits).
Remember, AOB represents Acceleration of Benefits meaning simply that when LTC claims are paid from the base policy, the life insurance death benefit (or base annuity), it is withdrawn which reduces dollar-for-dollar its value until it is exhausted. Once the base is zero, the continuation of benefits rider (aka COB) begins paying benefits until either the claim ends or the pool of money is exhausted.
And, remember this, if the policy is a joint policy – both spouses can receive maximum monthly benefits simultaneously. This is one of the benefits to the unlimited benefit duration – they will never run out of benefits while on claim.
Also, remember that there are a boatload of premium solutions available for the Care Solutions products which allows you to create both a benefit strategy and a funding strategy that is unique to your client’s requirements.
This example of Asset Care 2024 (initial rollout) shows the breakout of base and continuation of benefits.
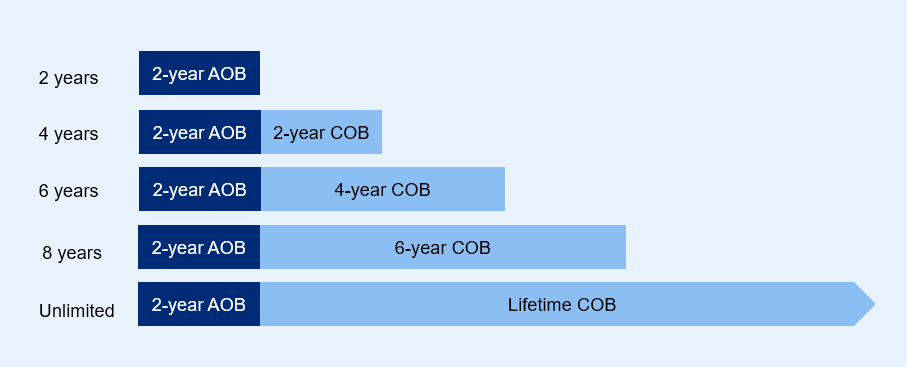
(Note: upcoming revisions to Asset Care have added an new base benefit duration of 3 years and the Annuity Care products offer different base benefit durations.)
Another thing to remember here is that Asset Care can be funded via single premium, recurring premiums, or a combination of the two. And, Annuity Care can be either single premium or a combination for single and recurring premium. I will begin discussing each of these including case studies starting in October.
One final product design note, all Care Solutions products include the OneAmerica Financial Care Benefits (Claims) Concierge which is staffed by OneAmerica personnel in Indianapolis.
For more information about the design options, contact Kelley Hilliard at (844)623-4251 or via email at kelleyhilliard.isp@oneamerica.com.

 Fridays with Fisher

Leave a comment